
FAQ
Got a question? Let us help you with that.
If you are looking for finance it’s understandable to have questions, so we’ve put together some answers to common questions you might be looking for.
What is a Home Equity Line of Credit (HELOC)?
A Home Equity Line of Credit (HELOC) in the UK is a flexible, revolving secured loan usually set up as a second-charge mortgage. It lets you borrow against your home’s equity, draw funds in stages, and pay interest only on the amount you actually use. Limits typically range from £5,000 to £500,000, capped at an 85% combined loan-to-value
How a UK HELOC Works
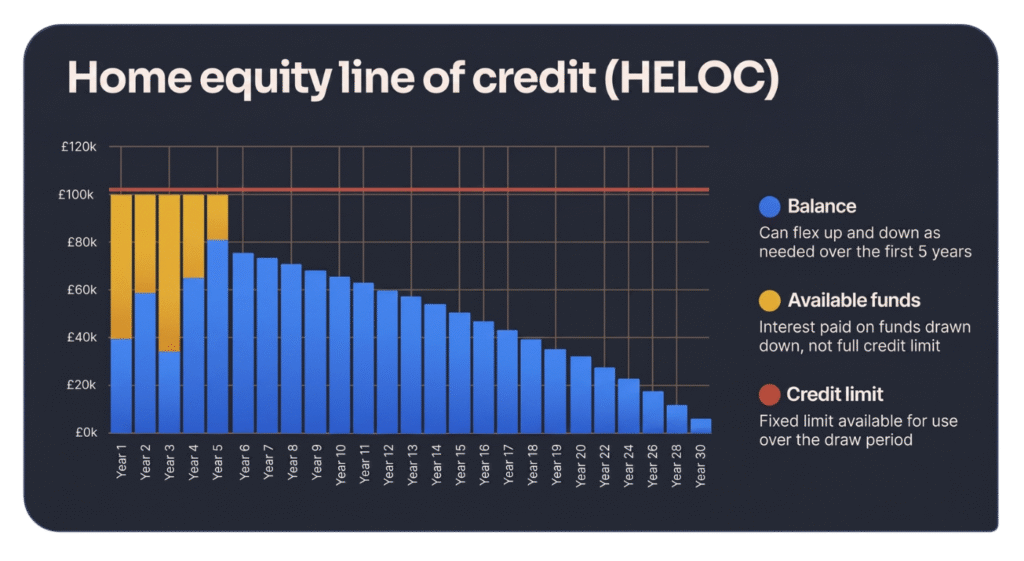
Draw Period: Lasts about 2 to 5 years. You can withdraw, repay, and redraw money as needed up to your limit.
Repayment Period: After the draw phase ends, the remaining balance converts into a standard repayment schedule over a fixed term (up to 30 years).
Preserving Your Mortgage: Because it often acts as a second charge, your primary fixed-rate mortgage remains untouched.
How much can I borrow and for how long?
You can borrow between £5,000 and £500,000, depending on the equity available in your property. The total term can range from five to thirty years and includes a flexibility period of two to five years at the start of the loan.
What can I use my loan for?
You can choose to upgrade your home with a new kitchen or extension for your family to enjoy, put down a deposit on a second home or trade up your car to the next model. Many customers also choose to use their funds to pay for school fees or treat themselves to a special holiday. You can also use the HELOC to consolidate existing loans. If you are thinking of consolidating debt, you should be aware that you may be extending the terms of the debt and increasing the total amount you repay.
What's the difference between a Home Equity Loan and a HELOC?
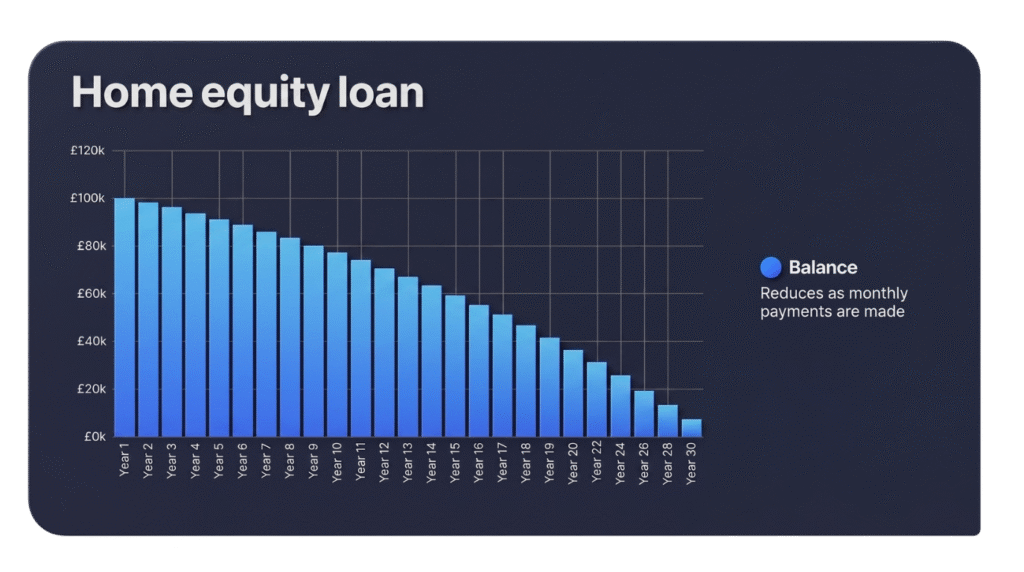
Home Equity Loan: You receive a one-off lump sum with fixed monthly repayments. You can choose between fixed or variable interest rates, making this option a good fit for big, planned expenses like home improvements or debt consolidation.
HELOC (Home Equity Line of Credit): This works more like a flexible credit facility. You can borrow funds as and when you need them, up to your approved limit. You only pay interest on the amount you actually draw, helping you keep borrowing costs down. This makes it ideal for ongoing or unexpected expenses, such as school fees or phased home projects.
What is the flexibility period?
The flexibility period (sometimes called the drawdown period) is the first 2, 3, 4, or 5 years of your HELOC. During this time, you can borrow, repay, and borrow again – all within your approved credit limit. You only pay interest on what you’ve actually borrowed. Each withdrawal is repaid over the remaining term of the loan. This gives you freedom to access funds when you need them, while keeping repayments structured and manageable.
What is the repayment period?
Once the flexibility period ends, the loan moves into the repayment period — this is when you pay back what you’ve borrowed in regular monthly instalments.
For example: A 5-year flexibility period + 10-year repayment period = 15-year total term.
Monthly payments are due throughout the full term if you have a balance. However, when we assess affordability, we focus on the repayment period (the last 10 years in this example) to make sure the HELOC can be comfortably repaid in full.